01 · WHY DOCUMENTS EXIST
The bank needs a coherent client picture.
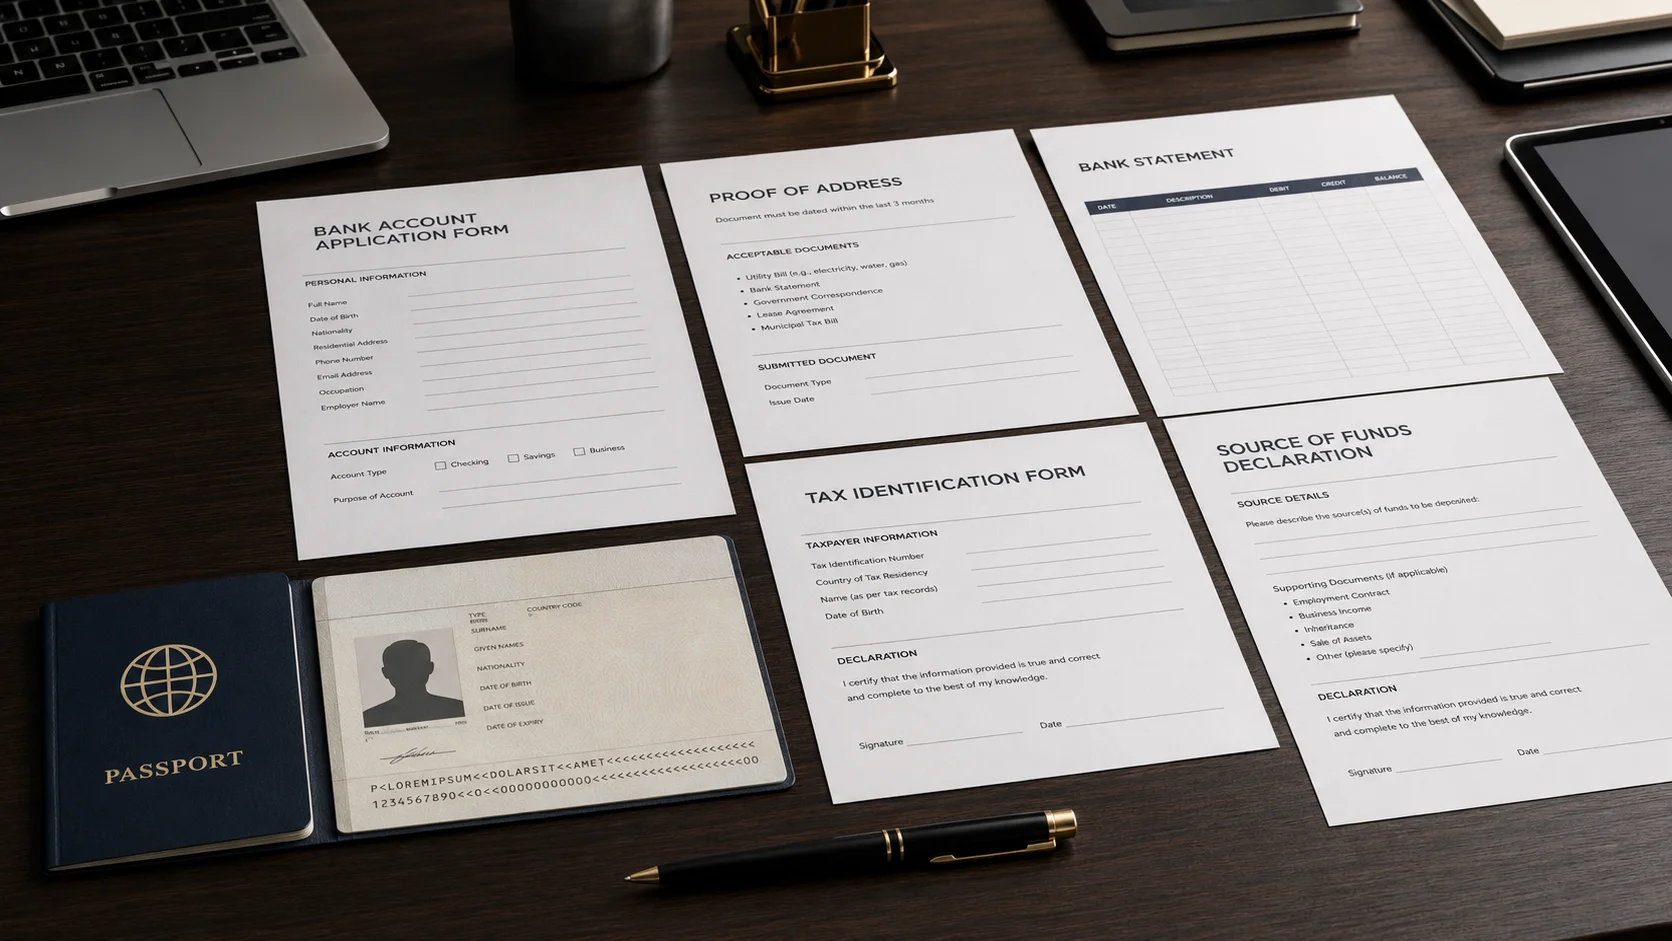
Customer due diligence is more than identifying a name. A bank must understand who the client is, who ultimately controls the account, why the relationship is being opened, and whether future transactions make sense against that profile.
International applications usually create more variables: another tax residence, foreign documents, cross-border transfers, unfamiliar companies, multiple currencies, or assets accumulated in several places. The bank may therefore need more context than a domestic everyday account would require.
The exact checklist varies by bank, account type, jurisdiction, delivery channel, and risk assessment. A document accepted by one institution may be too old, insufficiently certified, or outside policy at another. Always obtain the current list directly from the bank before arranging notarisation or translation.
The central rule
Your documents, application answers, public information, and expected account activity should tell the same understandable story.
02 · IDENTITY & ADDRESS
Proving who and where.
Passport or national identity card
The bank checks legal name, date of birth, nationality, photograph, document number, validity, and signs of tampering. A video-identification step, selfie, or certified copy may be required.
Utility bill, official letter, or bank statement
The address document normally needs to show the applicant’s name, residential address, issuer, and a recent date. P.O. boxes and business addresses often do not establish where someone lives.
Residence permit or visa
Where product access depends on local or regional status, a bank may require evidence of permission to live or work in that jurisdiction.
Published examples show how bank policies differ: Swissquote lists an identity document and proof of residence for its account-opening route, while DBS Singapore sets out different evidence depending on an applicant’s status. These examples are useful orientation—not universal standards.
03 · TAX RESIDENCE
Explaining where you are reportable.
Banks commonly request a tax self-certification identifying each jurisdiction of tax residence and the corresponding tax identification number, or a permitted explanation if a number is unavailable.
Nationality, residence, domicile, and tax residence are not interchangeable. Someone may have more than one relevant jurisdiction, and a recent move can create additional questions. The bank does not decide your tax residence for you; it collects and tests information to meet its obligations.
- Tax self-certification. A signed declaration of tax residence and reportable status.
- Tax identification number. The relevant TIN for each declared jurisdiction, where issued and required.
- Supporting evidence. A tax assessment, residence certificate, or official correspondence where the profile requires clarification.
- US indicators where relevant. US citizenship, birthplace, residence, or other indicia can lead to FATCA forms and additional evidence.
If you are uncertain about your status, obtain qualified tax advice before completing the form. Guessing can create contradictions that delay the application and may create reporting problems later.
04 · WEALTH & FUNDS
Two questions that sound similar—but are not.
-
Source of wealth How the client accumulated their overall wealth over time: employment, business ownership, investments, inheritance, property, or another legitimate path.
-
Source of funds Where the specific money entering this account comes from: a named bank account, asset sale, dividend, salary payment, company distribution, or inheritance transfer.
A founder may explain wealth through years of company ownership and provide company accounts, ownership records, or a sale agreement. The opening funds might then be traced more narrowly through a sale-closing statement and bank statements showing the proceeds arriving and being transferred.
| Scenario | Possible supporting evidence |
|---|---|
| Employment income | Employment contract, payslips, tax returns, and statements showing salary credits. |
| Business ownership | Company registry extracts, shareholder records, audited accounts, dividend resolutions, and tax filings. |
| Sale of a company | Share-purchase agreement, closing statement, professional correspondence, and bank trail. |
| Property sale | Purchase and sale contracts, land-registry evidence, completion statement, and receipt of proceeds. |
| Investments | Custody statements, transaction history, realised-gain reports, and original funding evidence where needed. |
| Inheritance or gift | Will, probate or estate documents, gift agreement, donor information, and transfer trail. |
The strongest evidence creates a traceable sequence. A one-line statement saying “savings” may describe the category, but it rarely explains a substantial international transfer on its own.
05 · COMPANIES & STRUCTURES
The bank must look through the entity.
A company, trust, or foundation account adds a legal layer, but due diligence still aims to identify the natural people who ultimately own, control, direct, or benefit from the structure.
- Formation documents. Certificate of incorporation, constitutional documents, partnership agreement, trust deed, or foundation charter.
- Current registry evidence. Commercial-register extract, certificate of incumbency, registered office, and good-standing evidence where applicable.
- Ownership and control. Share register, organisation chart, beneficial-owner declaration, and documents for each relevant natural person.
- Authority to act. Board resolution, authorised-signatory list, powers of attorney, and specimen signatures.
- Real business activity. Website, contracts, invoices, financial statements, tax filings, licences, offices, staff, suppliers, and customers.
- Account purpose. Expected countries, counterparties, transaction values, currencies, and the commercial reason for this banking location.
Complexity is not automatically unacceptable, but unexplained complexity is difficult to approve. A structure should have a defensible legal and commercial purpose that the documents support.
06 · FOLLOW-UP QUESTIONS
Why an application can pause.
Most follow-ups are triggered by missing context, outdated evidence, or contradictions—not simply by the number of documents submitted.
Common friction
- Different spellings or addresses across records.
- Scans with missing corners, glare, or unreadable text.
- Expired identity documents or address proofs outside the accepted age.
- Transfers arriving from an unexplained third party.
- Declared income that does not explain the relationship size.
- A company’s stated activity differing from its public footprint.
Higher-risk review
- Politically exposed persons and close connections.
- Links to sanctioned or higher-risk countries.
- Layered ownership across several jurisdictions.
- Cash-intensive, regulated, or higher-risk industries.
- Unusual asset growth or transaction patterns.
- Adverse information that requires clarification.
A PEP classification is a risk factor, not a finding of wrongdoing. FATF guidance treats the additional measures as preventive. Banks may require senior approval, stronger source-of-wealth corroboration, and closer ongoing monitoring.
07 · PREPARATION
Build a review-ready file.
- Request the bank’s current checklist. Confirm recency, certification, translation, format, and original-document rules before spending money.
- Create a one-page profile. Summarise residence, tax status, profession or business, account purpose, expected activity, and funding.
- Map each claim to evidence. If wealth came from a business sale, show ownership, the transaction, receipt of proceeds, and the transfer path.
- Check consistency. Names, dates, addresses, ownership percentages, figures, and explanations should reconcile across every file.
- Keep originals untouched. Do not edit official documents. Provide translations, annotations, or explanations as separate clearly identified files.
- Expect an update cycle. Banks may ask for refreshed records during onboarding and throughout the relationship.
Good preparation cannot guarantee approval. It can, however, make the profile easier to understand, reduce avoidable questions, and help identify early when a bank’s requirements do not fit the client.